Gold has always been more than jewellery in India.
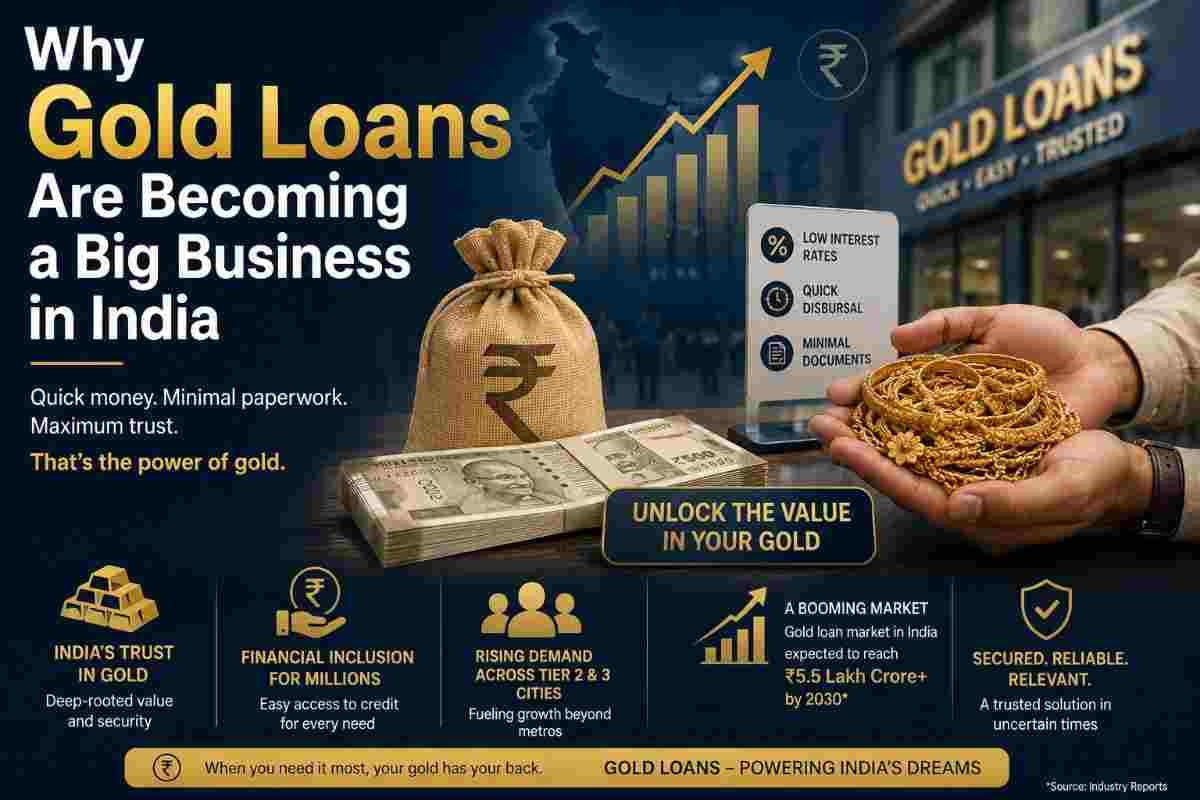
For millions of households, it is also a financial asset that can be converted into cash when money is needed.
That is one reason the gold-loan business is attracting so much attention in 2026.
Recent reporting shows that loans against gold have been growing rapidly, while large financial groups are entering or expanding in the segment. The appeal is straightforward: lenders get a physical asset as collateral, while borrowers can access funds without selling their gold.
Why the market is growing
The biggest reason is simple: India has an enormous amount of household gold.
For decades, families have accumulated gold as jewellery and savings. Much of that wealth is not sitting in a bank account or investment portfolio.
Gold loans create a bridge between that stored wealth and the formal credit system.
A borrower can pledge gold, receive a loan and later recover the jewellery after repayment.
That can be particularly useful for small businesses, self-employed workers and households that need short-term liquidity.
High gold prices change the equation
Gold prices have risen sharply in recent years.
That means the same piece of jewellery can support a larger loan than it could previously, subject to regulatory and lender limits.
For lenders, higher-value collateral can make the segment attractive.
For borrowers, it can provide access to money without selling an asset that may have family or emotional value.
But borrowers still need to remember that a gold loan is debt.
If the loan is not repaid according to the agreement, the pledged gold can ultimately be auctioned under the applicable rules.
Why large companies are entering
The market is no longer limited to traditional gold-loan specialists.
Recent reports have highlighted interest from major Indian business groups and financial companies, including Aditya Birla Group, Tata Capital and Godrej Capital.
Their interest shows how mainstream the category is becoming.
Large players can bring technology, capital, digital onboarding and wider distribution.
That could make borrowing against gold easier for customers.
It could also increase competition for established regional lenders.
Gold loans can be useful, but they are not cheap money
The biggest misconception is that a secured loan is automatically a cheap loan.
Interest rates, processing charges, valuation fees, penalties and other costs can vary between lenders.
Borrowers should compare the total cost rather than choosing a lender simply because the loan amount looks attractive.
They should also understand the repayment schedule and what happens if payments are delayed.
The regulatory side matters
The Reserve Bank of India has been tightening and clarifying rules around lending against gold.
The objective is to protect borrowers and make lending practices more disciplined.
For lenders, stricter rules can mean higher compliance costs.
For customers, they can also provide greater clarity around valuation, loan-to-value limits and auction procedures.
A growing market needs that discipline.
What this means for India's lending industry
Gold loans occupy an interesting space between traditional banking and household finance.
They can help formalise borrowing for customers who may not have strong conventional credit profiles.
They can also provide lenders with a secured asset.
The challenge is scale.
As more large companies enter the market, customer acquisition may become more expensive and competition may push lenders to improve digital experiences and pricing.
Technology will probably play a bigger role too.
Digital gold valuation, faster approvals, online repayments and better customer communication can reduce friction.
The bigger picture
The gold-loan boom says something important about the Indian economy.
Household assets are increasingly being connected to formal financial services.
Instead of gold simply sitting in a locker, it can become collateral for education, business working capital, emergencies or other needs.
But that does not mean every household should borrow against gold.
The right question is whether the loan solves a genuine financial need and whether the borrower has a realistic repayment plan.
The bottom line
Gold loans are becoming a bigger part of India's financial landscape because the country has a huge pool of household gold, borrowers need flexible credit and lenders see an attractive secured-loan opportunity.
As large financial players enter, customers may get more choices.
That is good for competition.
But more choices also mean borrowers need to compare interest rates, fees, repayment terms and auction conditions carefully.
Gold may be valuable.
A gold loan still has to be managed like any other debt.
Why borrowers choose gold loans
A gold loan can be attractive because it is based on collateral rather than only on the borrower's conventional credit profile.
For someone running a small business, a delay in receiving a payment can create a short-term cash problem. Selling jewellery may feel like a permanent decision. A secured loan can offer a temporary bridge if the borrower understands the cost and repayment obligation.
That flexibility helps explain why gold loans have remained relevant across both urban and smaller markets.
The digital experience is changing
Traditional gold-loan businesses often relied on physical branches and local relationships.
Digital financial services are changing that model.
Customers can increasingly discover lenders online, check basic eligibility, receive information about terms and manage repayments digitally. Physical gold valuation and verification still require processes on the ground, but the customer journey around them can become faster.
For lenders, technology can also improve record keeping and risk management.
Competition could change pricing and service
When large financial companies enter a category, customers generally get more choices.
Lenders may compete on interest rates, processing speed, branch networks, digital convenience and service quality.
Established gold-loan companies have an advantage in experience and local trust. New entrants may have an advantage in technology and distribution.
That competition could make the market more professional.
The risks should not be ignored
Gold loans are secured, but they are not risk-free.
The borrower still has an obligation to repay. If the loan remains unpaid and the account reaches the relevant enforcement stage under the lender's terms and applicable regulations, the pledged gold can be sold.
Customers should therefore understand the agreement before borrowing.
They should also compare the total cost of the loan rather than focusing only on the headline interest rate.
Why this matters for the wider economy
Gold loans sit at an interesting intersection of household wealth and formal credit.
India has a huge amount of privately held gold. Bringing some of that asset base into the formal lending system can increase access to capital.
For small businesses, that capital can sometimes support working capital or expansion.
For households, it can help manage a temporary liquidity need.
But the long-term value comes from responsible borrowing.
The gold-loan industry can grow quickly only if lenders maintain customer trust and borrowers understand the financial commitment they are taking on.
A practical way to think about gold loan business India 2026
The easiest mistake when reading business news is to look for a single number that explains everything.
Markets and businesses rarely work that way.
A headline can tell you that activity is rising, but it does not tell you whether every company in the sector will benefit. A funding announcement can show that investors are interested, but it does not prove that the business will become profitable. A new technology can create a major opportunity, but implementation can still fail.
The useful habit is to connect the headline to the underlying business model.
Who is paying?
Why are they paying?
What does it cost to serve them?
What could make the economics better or worse?
What changes if the market becomes more competitive?
Those questions are useful whether you are an investor, entrepreneur or simply someone trying to understand India's economy.
The other important habit is to separate a trend from a guarantee.
A trend tells us where activity is moving. It does not tell us exactly where the next winner will come from.
That distinction is particularly important in fast-moving areas such as technology, IPOs, startups and financial services. New companies can grow quickly, but competition can also appear quickly. Regulations can change. Consumer preferences can shift. Capital can become more expensive.
For readers, this means the most valuable business stories are not necessarily the ones with the most dramatic headlines.
They are the stories that explain what changed, why it changed and what could happen next.
That is the lens through which this trend should be viewed.
What readers should watch next
Over the coming months, pay attention to the practical signals behind the trend.
Look for companies reporting real revenue growth rather than only announcing plans. Watch whether customers continue using a product after the initial launch. Look at whether businesses can improve margins as they scale. Notice whether investment is creating new capacity, new jobs or new products.
Also watch what happens when the market becomes less supportive.
A strong business should have a strategy for difficult periods, not only good ones.
That is often where the difference between a genuine long-term trend and a short-lived boom becomes visible.
For India, the broader opportunity remains significant. A large domestic market, a growing digital economy, improving infrastructure and an increasingly connected business ecosystem create room for new companies and new business models.
But opportunity alone is not enough.
Execution will decide who benefits.
What a stronger gold-loan market could mean for customers
If competition continues to increase, customers may see better digital services, faster processing and more transparent communication. Lenders will also have to work harder to build trust because the asset being pledged is often emotionally important to the borrower.
For the industry, scale will matter, but trust may matter even more.
A lender that explains the loan clearly, values collateral fairly and communicates properly when a borrower faces difficulty can build a stronger relationship than one that focuses only on rapid disbursal.
That is why the next phase of the gold-loan business will probably be about more than loan growth. It will also be about customer experience, compliance and responsible lending.
For borrowers, the basic rule remains simple: borrow only when the need is clear, compare the total cost and understand the consequences of missed payments before pledging an asset.
Gold may have a long history as a store of value. Turning it into credit still requires a careful financial decision.
Disclaimer: This article is for informational purposes only and is not investment, financial or business advice.