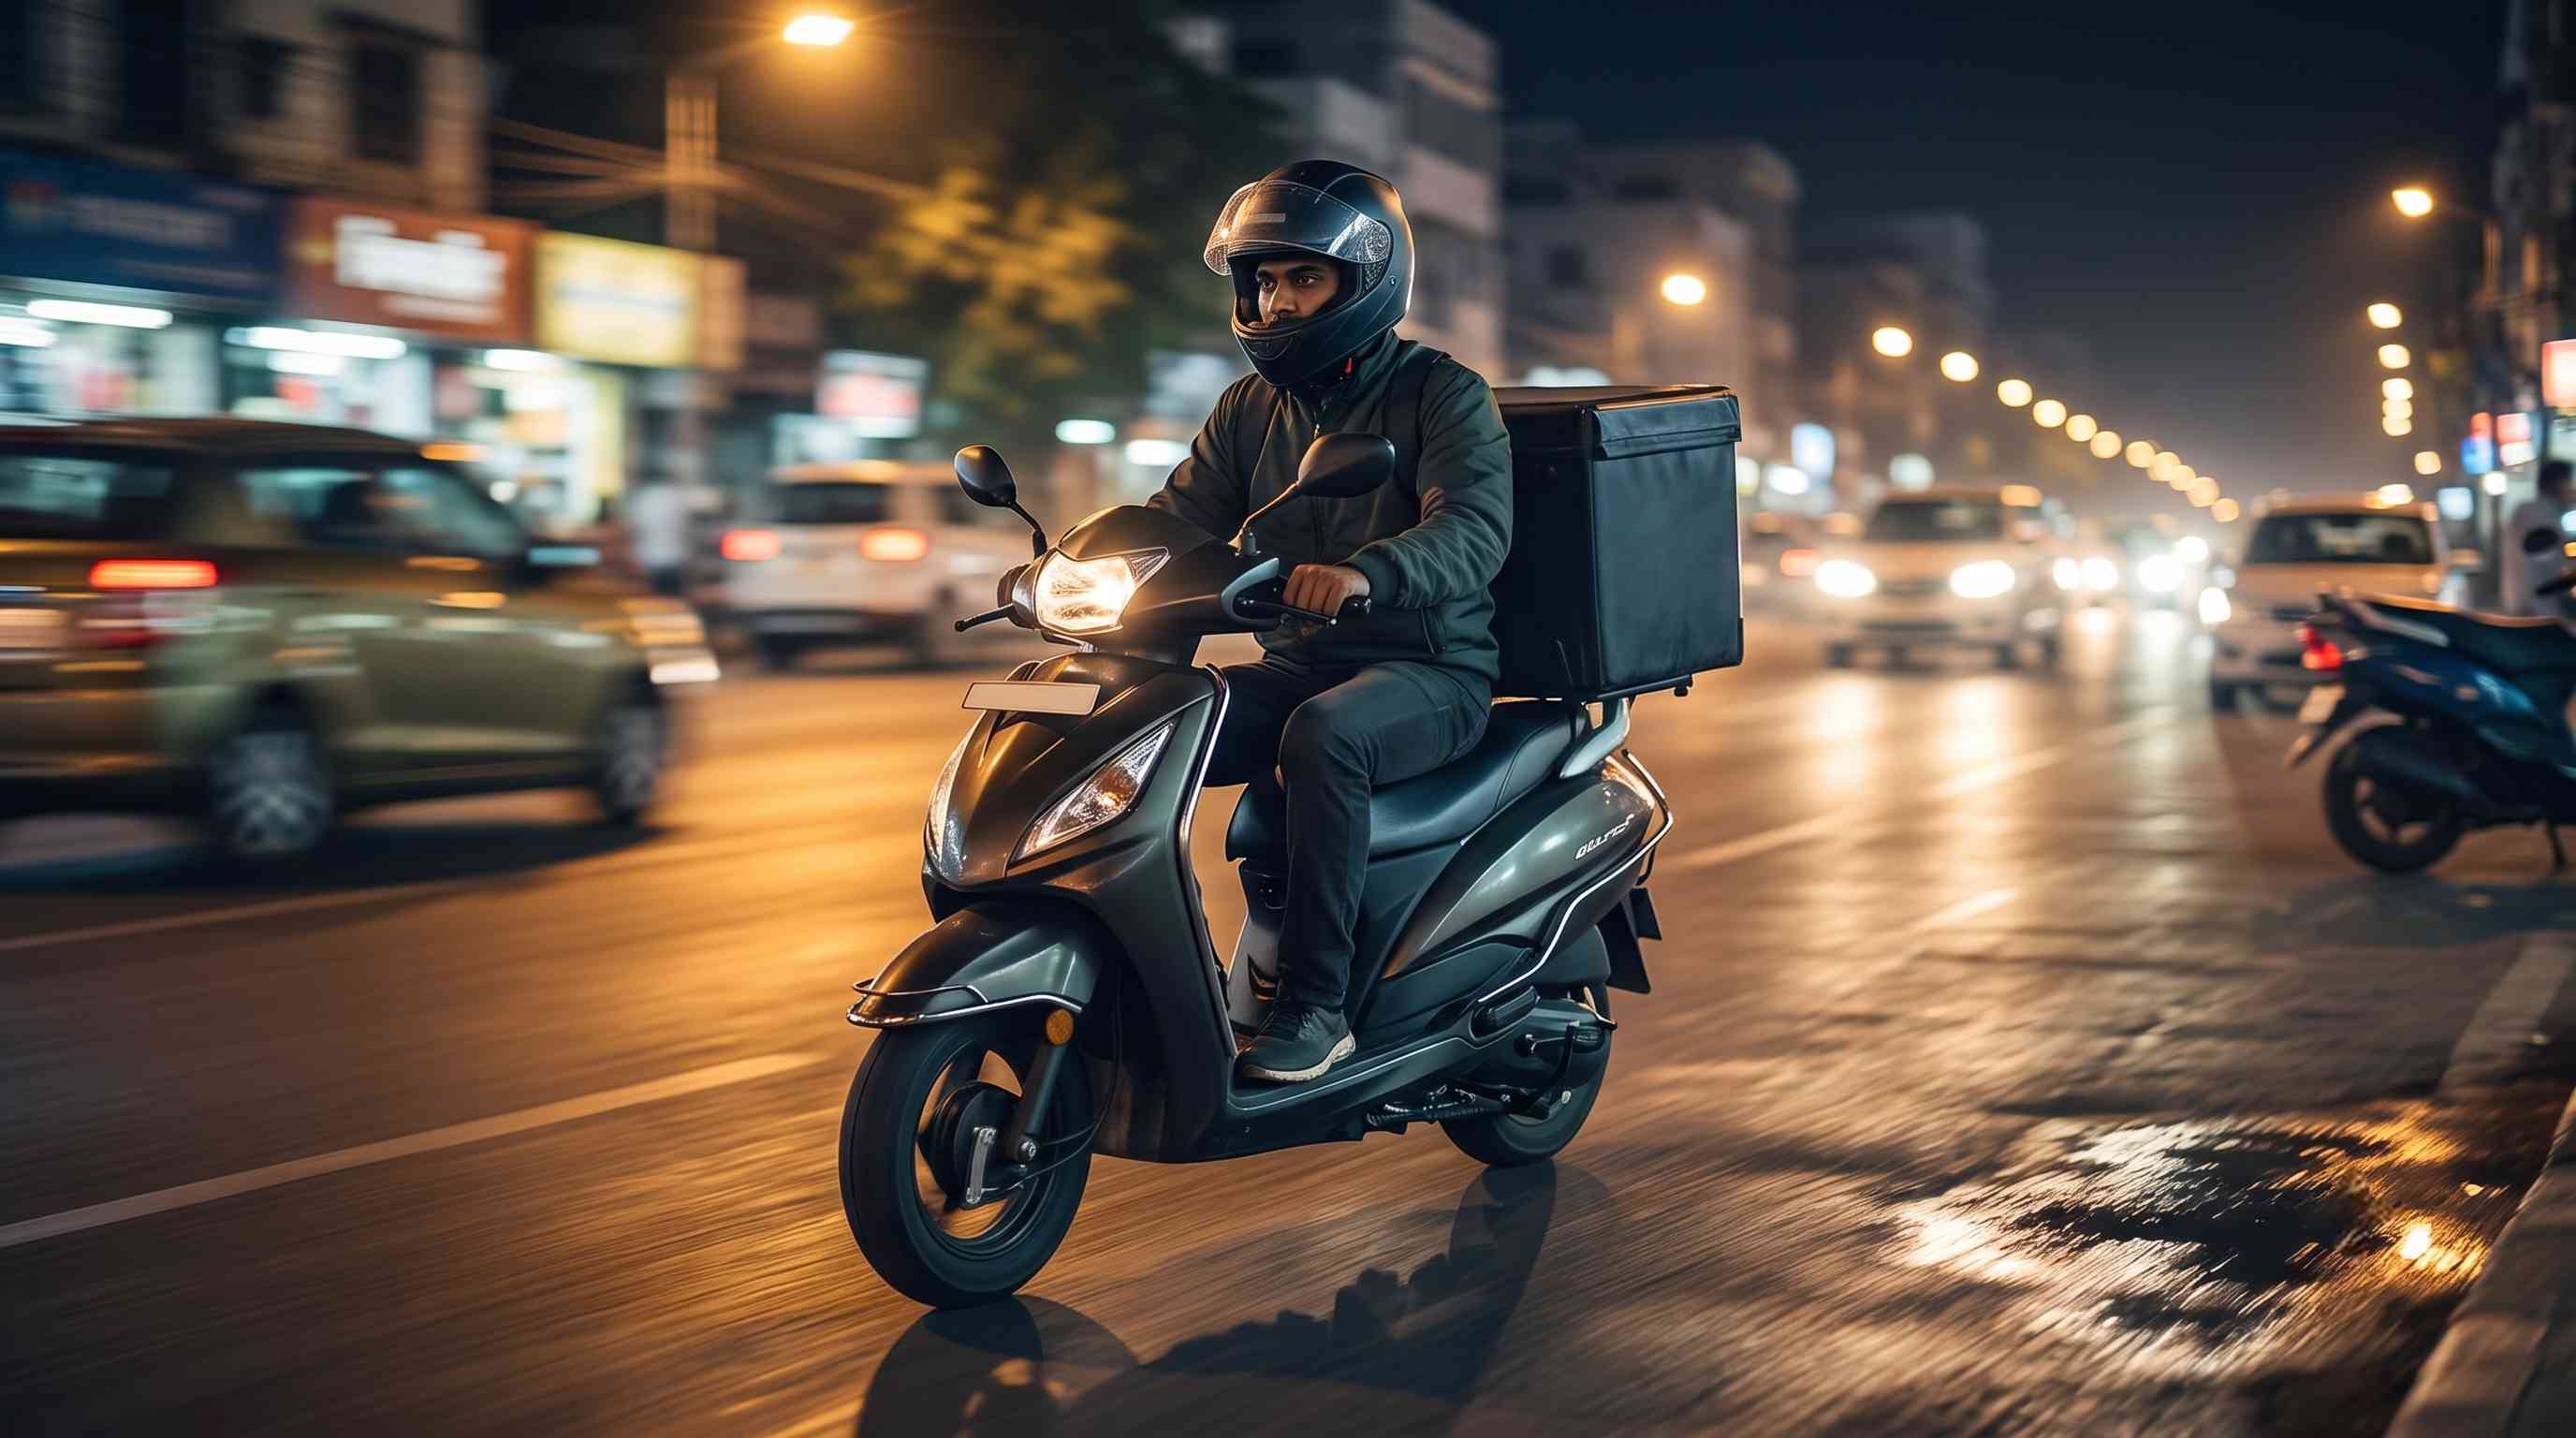
Quick commerce — ultra-fast delivery of groceries and daily essentials — has been one of India's fastest-growing consumer internet categories. It's also one of the most capital-intensive, which is why investors watch these businesses' path to profitability as closely as their growth rates.
Why quick commerce is expensive to run
Delivering orders within 10-20 minutes requires a dense network of "dark stores," delivery riders on standby, and inventory held closer to customers than a traditional warehouse model. That infrastructure costs money regardless of how many orders come through it, which is why growth in this category has historically come with heavy losses.
What "improving unit economics" actually means
When a quick-commerce business talks about improving unit economics, it usually points to a combination of:
- Higher order density per dark store, spreading fixed costs across more deliveries
- A rising share of repeat customers, which lowers the marketing cost needed to generate each order
- Lower logistics and last-mile delivery costs as networks mature and routing improves
Growth alone isn't the full picture
A high year-on-year growth rate sounds impressive, but it matters less than whether losses are narrowing as the business scales. A company that grows quickly while losses widen at the same pace is simply buying market share; one that grows while losses narrow is starting to build a sustainable business model.
What to watch in this sector
For anyone following quick-commerce and foodtech companies, the more useful metrics beyond headline growth are: order frequency from repeat customers, delivery cost per order, and the trend in losses relative to revenue over several quarters — not just one strong quarter in isolation.
The takeaway
Rapid growth in quick commerce is not inherently a red flag or a green light on its own. The businesses worth watching are the ones that can show growth and a credible, improving path to profitability at the same time.